Does Homeowners Insurance Cover Termite Damage?
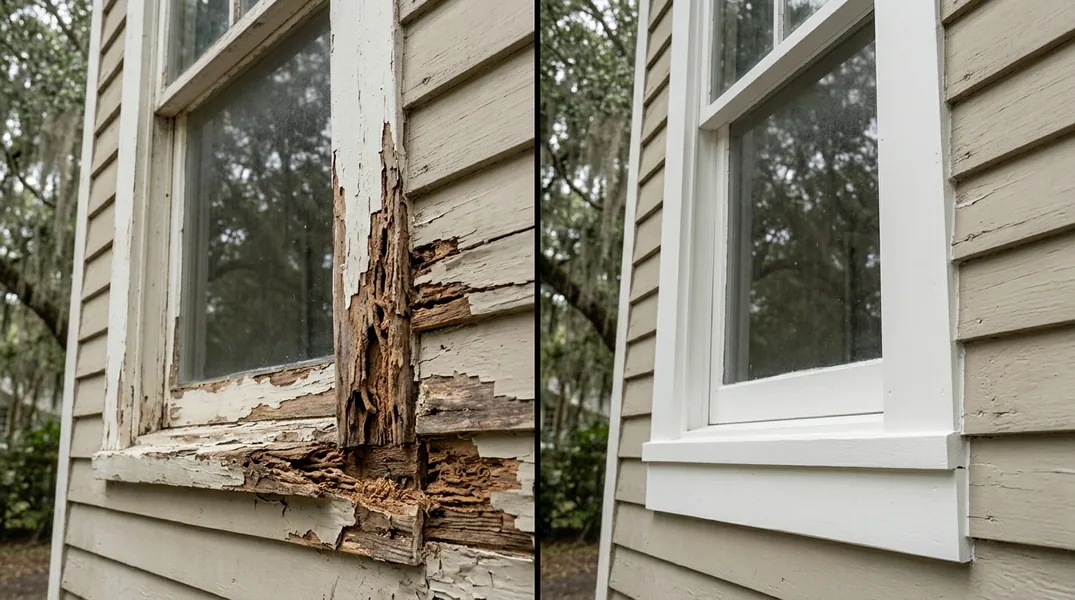
One of the most common questions homeowners in Mobile ask is whether their homeowners insurance will cover termite damage. Unfortunately, the answer is almost always no. Standard homeowners insurance policies explicitly exclude damage caused by insects, including termites, carpenter ants, and other wood-destroying pests. This exclusion exists because termite infestations are considered a maintenance issue that homeowners should have prevented through regular inspections and pest control measures.
The reasoning behind this exclusion is straightforward from an insurance perspective. Termite damage develops gradually over months or years, giving homeowners ample opportunity to detect and address the problem before it becomes catastrophic. Insurance is designed to cover sudden, unexpected events, not gradual deterioration that results from negligence or lack of preventive maintenance. If you discover termite damage in your home, the cost of Termite Damage Repair will typically come out of your own pocket.
However, there is one important exception to this rule. If a covered peril, such as a fire or storm, creates an opening in your home that allows termites to enter and cause subsequent damage, your insurer may cover the damage from the fire or storm itself, but still not the termite damage. This distinction is crucial for homeowners to understand when filing claims.
Hurricane and Storm Damage: What's Covered?
Living in Mobile, Alabama means hurricane season is a real concern for many homeowners. The good news is that wind and storm damage is typically covered by standard homeowners insurance policies, including damage from hurricanes, severe thunderstorms, and hail. If a hurricane tears off your roof, breaks windows, or causes wood damage to your home's structure, your insurance should cover the cost of repairs, subject to your deductible and policy limits.
Storm damage to wood framing, siding, and structural components is generally considered a covered loss because it results from a sudden, external event beyond your control. This means if a hurricane damages your home's wooden beams, causes wood rot to develop quickly due to water intrusion, or breaks floor joists, these repairs may be covered. However, the key is that the damage must be directly caused by the storm itself, not by pre-existing conditions or lack of maintenance.
One critical detail to understand is the difference between hurricane damage that occurs during the storm and secondary damage that develops afterward. If your roof is damaged during a hurricane and you don't have it tarped or repaired promptly, resulting water damage and wood rot may not be fully covered because they could have been prevented. Insurance companies expect homeowners to take reasonable steps to mitigate additional damage after a covered loss occurs.
Wood Rot Insurance Claims: Coverage Depends on the Cause
Wood rot is one of the most misunderstood issues when it comes to homeowners insurance. Whether your wood rot insurance claim will be approved depends entirely on what caused the rot in the first place. If wood rot develops due to age, poor ventilation, or lack of maintenance, it is not covered. However, if wood rot results from a covered peril like a storm, burst pipe, or fire damage, your insurance may cover the repair costs.
For example, if a hurricane damages your roof and water leaks into your attic for several weeks before you notice it, causing rot to develop in your rafters and beams, that damage may be covered because it directly resulted from the hurricane. On the other hand, if wood rot develops in your basement due to chronic moisture problems and poor drainage around your foundation, your insurance will almost certainly deny the claim because this is a maintenance issue.
The challenge with wood rot claims is that insurance adjusters must determine whether the rot is a direct result of a covered loss or a pre-existing condition. This is why it's essential to document everything and act quickly after a storm or water damage event. If you suspect wood rot is developing in your home, getting a professional assessment from Wood Rot & Dry Rot Repair specialists can help you understand the cause and provide documentation for your insurance claim.
Structural Damage and Floor Joists: Insurance Coverage Explained
Damage to structural elements like floor joists and beams is a serious concern for homeowners because it can affect the safety and value of your entire home. If storm damage causes your floor joists to crack, rot, or fail, your homeowners insurance should cover repairs as a direct result of the covered loss. However, if floor joists are damaged due to termite infestation or gradual wood rot from moisture, the cost of Floor Joist & Subfloor Repair will be your responsibility.
Subfloor damage is equally important to address promptly. A soft or sagging floor is often a sign of serious structural problems that require immediate attention. If the damage was caused by a sudden event like a pipe burst during a winter freeze or water damage from a hurricane, your insurance may cover it. But if the damage developed gradually over years due to poor ventilation or chronic moisture issues, you'll need to pay for repairs yourself.
One situation where structural damage gets complicated is when multiple factors contribute to the problem. For instance, if a storm damages your roof, water enters your home, and moisture accelerates existing wood rot in your floor joists, determining what portion of the damage is covered can be challenging. This is why having a detailed inspection and repair estimate from qualified professionals is invaluable when filing a claim.
How to File an Insurance Claim for Wood Damage in Mobile
If you've experienced storm damage or discovered wood rot that you believe should be covered by insurance, the first step is to contact your insurance agent or company promptly. Most policies require you to report damage within a specific timeframe, often 30 to 60 days. Document everything with photographs and written descriptions of the damage, including the date you discovered it and any events that may have caused it.
Next, get a professional inspection and detailed repair estimate. Insurance adjusters will want to see documentation from qualified contractors outlining the scope of work needed and the estimated cost. Having this information ready will strengthen your claim and speed up the approval process. When you're ready to move forward with repairs, make sure to get a free estimate from experienced professionals who can assess the damage accurately and help you communicate with your insurance company.
Be prepared for the possibility that your claim may be partially denied or require negotiation. Insurance companies sometimes dispute the cause of damage or argue that certain repairs fall outside the scope of coverage. If this happens, don't hesitate to ask your adjuster for a detailed explanation and consider hiring an independent inspector if you believe the denial is unfair. Having professional documentation of the damage and its cause is your best defense in these situations.
When to Call a Professional for Damage Assessment and Repair
Trying to determine whether damage is covered by insurance on your own is risky and often leads to missed opportunities or denied claims. Professional contractors and restoration specialists have experience working with insurance companies and understand what documentation adjusters need to approve claims. If you've experienced storm damage or noticed signs of wood rot or structural damage, calling a qualified professional should be your first step, even before filing a claim.
Mobile Carpentry serves homeowners throughout Mobile and the surrounding areas with expert assessment and repair services. Our team can evaluate your damage, determine the likely cause, and provide detailed documentation that supports your insurance claim. Whether you need Beam Replacement & Load-Bearing Wall Removal or assessment of water damage to your home's structure, we're here to help you navigate the insurance process and get your home restored properly.
Don't delay if you suspect structural damage or wood rot. The longer you wait, the worse the problem becomes and the harder it is to prove the original cause for insurance purposes. Contact Mobile Carpentry today at (251) 333-6112 or visit our website to request a free estimate and professional assessment of your home's condition.
Looking for a professional carpentry contractor in Mobile? Mobile Carpentry responds fast for all your carpentry needs.
Get a Free QuoteOur services: Wood Rot & Dry Rot Repair · Termite Damage Repair · Floor Joist & Subfloor Repair